Current's first product, a debit card for teens controlled by parents, launched in May 2017.
Current launched its personal accounts for adults in February 2019, which featured early access to wages with direct deposit, fee-free overdraft (up to $200), no minimum balance requirements, and instant removals of gas holds that stations put on debit cards.
In 2020, Current became the first U.S. based consumer fintech to launch a points reward system based on debit, which allows its members to earn points redeemable for cash back in their Current accounts.
In September 2020, Current launched an add cash feature through its partnership with InComm, giving its members the ability to add cash to their Current accounts at over 60,000 stores nationwide that is then instantly available in their Current accounts.
Read the full text
In January 2022, Current launched a 4% APY savings product.
In October 2022, Current launched crypto trading without fees in partnership with Zero Hash, giving its over four million members access to buy and sell dozens of coins on its platform without paying trading fees and with instant liquidity from trades.
Also in October 2022, Current announced it was now doing its own processing directly with Visa.
In August 2023, Current launched a secured credit building card in partnership with Cross River Bank. Current members can build their credit histories through a single spending balance on Current’s platform. The secured charge card connects to a members’ available spending balance.
In early 2024, Current launched Paycheck Advance, its earned wage access product, allowing members to access up to $750 of an upcoming paycheck in advance without any mandatory fees or credit checks. Earned wage access services allow workers to access wages they have already earned before their scheduled payday.
Operations
Business model
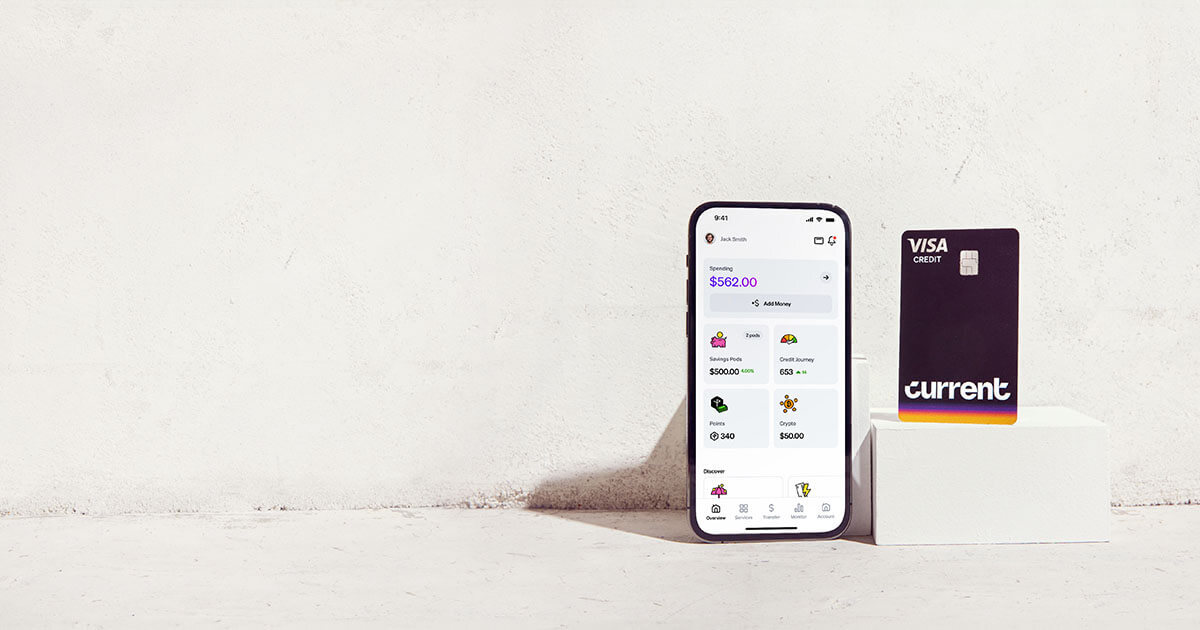
Current has no physical branch locations and does not charge overdraft fees or have a minimum balance requirement. Account holders are issued Visa debit or credit cards and have access to Current's online banking system via its mobile app for iOS or Android.
Current has a spend-based business model, earning revenue from interchange. Current Accounts have no monthly account fees.
In March 2025, Current announced the release of a new case study from Datos Insights titled ‘Foregoing BaaS: How Owning the Core Fuels Current’s Success,’ which concluded Current’s choice to build and not buy the core banking platform has been a defining factor in the company’s growth and success.
Patents
On December 12, 2019, the company applied for patent 16424341 / 20190378121, "Cryptographic Technology Platform And Methods For Providers To Enable Users To Monetize Their Data" that would cryptographically give end-users, i.e., customers, an option to maintain complete personal data privacy or opt to monetize all or part of it.
FDIC Insurance
Current accounts are insured up to the standard maximum deposit insurance amount of $250,000 through its bank partners, Choice Financial, Member FDIC and/or Cross River Bank, Member FDIC.
Current announced it had no plans at the present time to pursue its own bank charter in October 2020.